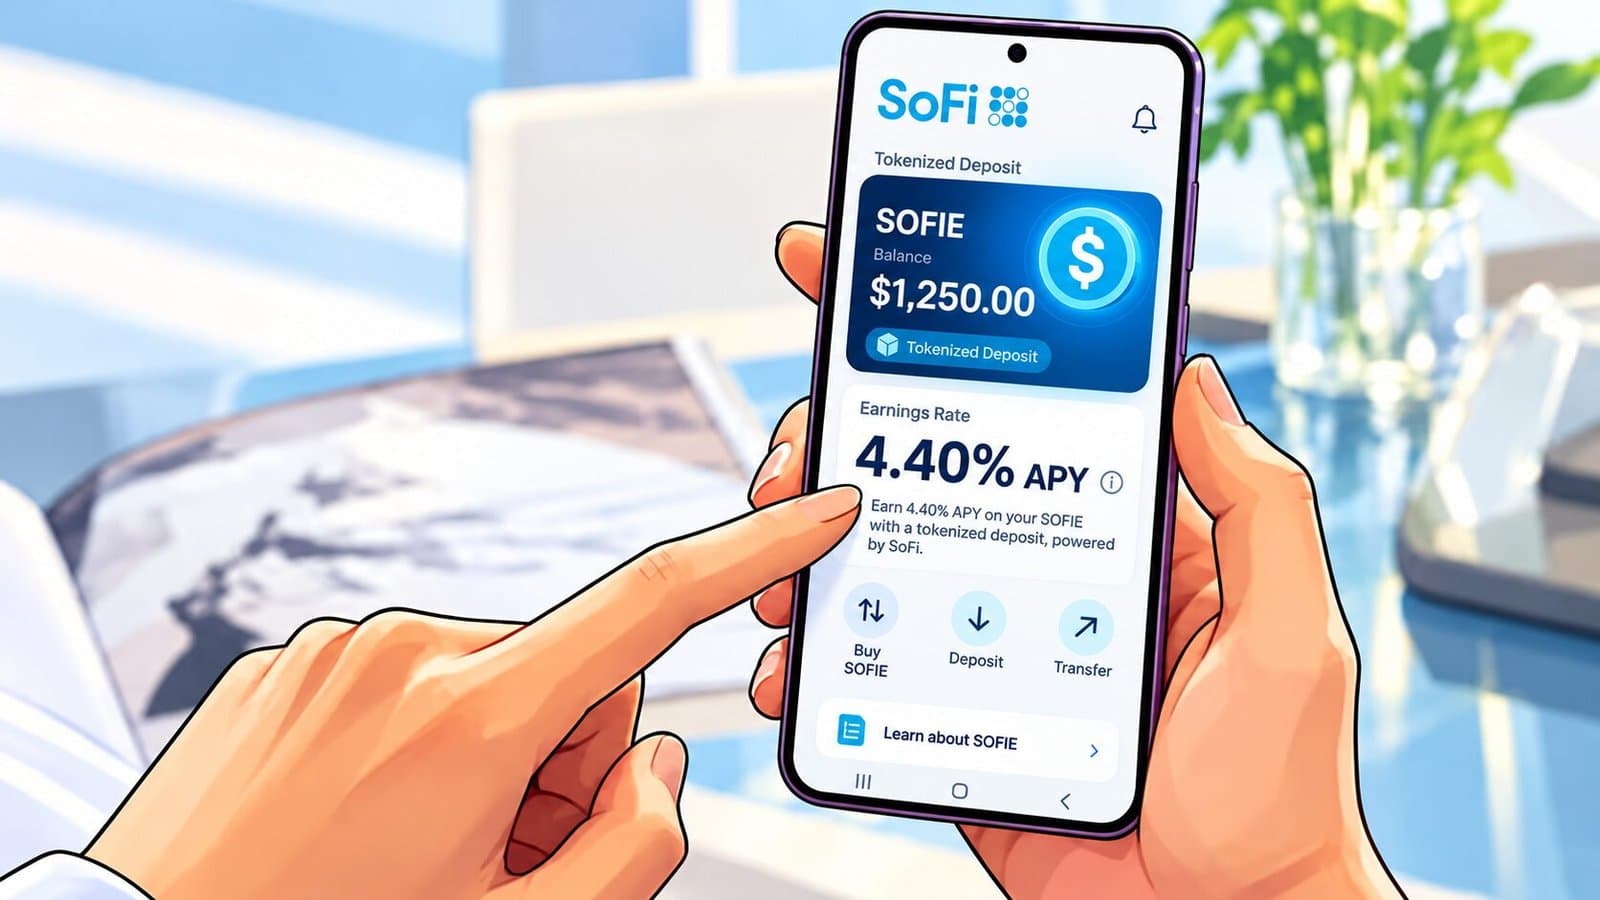
SoFi launched SoFi Earn, a tokenized deposit that pays 4.40% APY on digital dollars held for later use. Each token, SOFIE, represents $1 on deposit at SoFi Bank.
Balances carry FDIC insurance up to $250,000 per depositor, per insured bank, for each account ownership category.
The product is the company’s fifth digital-asset launch in under a year, SoFi said. It rolls out to SoFi Crypto members through November, and moves the bank into territory long held by non-bank firms.
SoFi points to an estimated $64 billion of idle stablecoins
SoFi cites Federal Reserve Bank of Kansas City research estimating that 21.2% of stablecoin supply sits idle. That equates to about $64 billion against the study’s November 2025 reference market of $300.5 billion.
The tokenized deposit is pitched at that liquidity. Many stablecoins pay no interest and are not FDIC-insured.
The rate is variable and was current as of October 20. There is no minimum balance, and SoFi says fees may reduce earnings.
“Too much money in the digital asset ecosystem is sitting idle, leaving massive potential earnings on the table for millions of people.” — Anthony Noto, chief executive officer of SoFi, in the company’s announcement
Payments are 0.7% of supply, and the idle share is modeled
The estimate comes from a Payments System Research Briefing by Franklin Noll, published April 10.
Noll puts trading assets at 48.8% of supply, transfers at 29.3%, idle at 21.2% and payments at 0.7%. He writes that the exercise “involves some guesswork,” and the idle share is a modeled assumption.
Idle also covers balances in forgotten or lost wallets, which no product can reach. The addressable pool is smaller than the headline figure.
The tokenized deposit is not the stablecoin, and that is the design
SoFi runs two instruments rather than one. SOFIE is the interest-bearing deposit. SoFiUSD is the stablecoin that moves.
Members convert SOFIE one-for-one into SoFiUSD to transact, then buy digital assets in the app or send funds over blockchain rails continuously.
At conversion, the balance stops being a bank deposit. SoFiUSD carries no FDIC insurance, and the SOFIE rate no longer applies.
The GENIUS Act excludes deposits from its stablecoin definition
The GENIUS Act bars payment stablecoin issuers from paying holders interest or yield solely in connection with holding, using or retaining the stablecoin. It does not reach deposits.
The OCC addressed this directly in its final rule. The GENIUS Act’s yield prohibition “does not apply to deposits,” it wrote.
The statutory definition of a payment stablecoin “explicitly excludes deposits, regardless of whether the deposit is recorded using distributed ledger technology,” the rule states.
So SOFIE sits outside the prohibition as a matter of statutory definition, not interpretation.
More on stablecoin payments:
Circle backs UN stablecoin payments as WFP cuts food aid
SoFi has been assembling the pieces since 2025
SoFi became the first nationally chartered bank to offer digital-asset trading to consumers in November 2025. Members can trade more than 40 assets.
It issued SoFiUSD in December 2025, which it describes as the first stablecoin from a US national bank. SoFiUSD handles card settlement for SoFi’s entire card program across Mastercard’s payments network.
Big Business Banking followed earlier in 2026, giving companies one platform for fiat and digital assets. The tokenized deposit is the layer that sits before any of it moves. SoFi reports 15.8 million members.
Key numbers behind the SoFi tokenized deposit
- The SoFi Earn tokenized deposit pays 4.40% APY, variable, with rates current as of October 20, 2026 (SoFi, October 22, 2026)
- Balances are FDIC-insured up to $250,000 per depositor, per insured bank, per ownership category (SoFi, October 22, 2026)
- Kansas City Fed research estimates 21.2% of stablecoin supply is idle and 0.7% is used for payments (Federal Reserve Bank of Kansas City, April 10, 2026)
- SoFi reports 15.8 million members and more than 40 tradable digital assets (SoFi, October 22, 2026)
- The OCC final rule implementing the GENIUS Act takes effect January 18, 2027 (OCC Bulletin 2026-50, October 21, 2026)
A separate yield fight is running alongside
The OCC finalized its GENIUS Act rules on October 21, effective January 18, 2027. One change drew most of the comment.
The proposal would have presumed that certain arrangements between issuers and affiliates or related third parties violated the yield prohibition. The final rule eliminates that presumption.
This concerns indirect yield on payment stablecoins, not the tokenized deposit question settled above. The OCC says it retains anti-evasion authority and will assess arrangements case by case.
“We are providing a clear, practical framework for payment stablecoin innovation, with strong standards for reserve backing, redemption, and risk management.” — Jonathan Gould, Comptroller of the Currency, as reported by the ABA Banking Journal
More on bank-issued digital dollars:
Samsung Wallet gets stablecoin payments in late October
Banks wanted the presumption kept and said so
The American Bankers Association had urged the OCC to strengthen the language. The final rule moved the other way.
Rob Nichols, the association’s president and chief executive, said issuers can provide economically equivalent yield while technically avoiding the statutory prohibition.
He argued the outcome threatens the deposit base banks lend from, and undercuts the distinction Congress drew between payment stablecoins and bank deposits.
“The result is a final rule that will preserve the status quo for crypto platforms despite Congress’s clear intent to protect local lending.” — Rob Nichols, president and chief executive of the American Bankers Association, in a statement on the final rule
What to watch on the tokenized deposit model
SoFi has taken the route the statute marks out for a tokenized deposit. Keep the yield in an insured bank deposit, and use a separate stablecoin only for movement.
That model is available to deposit-taking banks. It does not make the payment stablecoin itself yield-bearing.
Payment stablecoin issuers remain barred from directly paying holders yield solely for holding, using or retaining the stablecoin.
Watch whether other chartered banks follow with a tokenized deposit of their own.
The OCC expects to revisit indirect yield
European banks backing stablecoins face it under a different rulebook. The OCC said it expects to propose clarifying rulemaking on indirect yield once it has more supervisory experience.