Coastal Financial shares closed at $37.55 on 28 September 2026, down 16.23% in a single session. The selloff followed Valley National Bancorp’s agreement to buy Bluevine, a small-business fintech that banks its customers through Coastal.
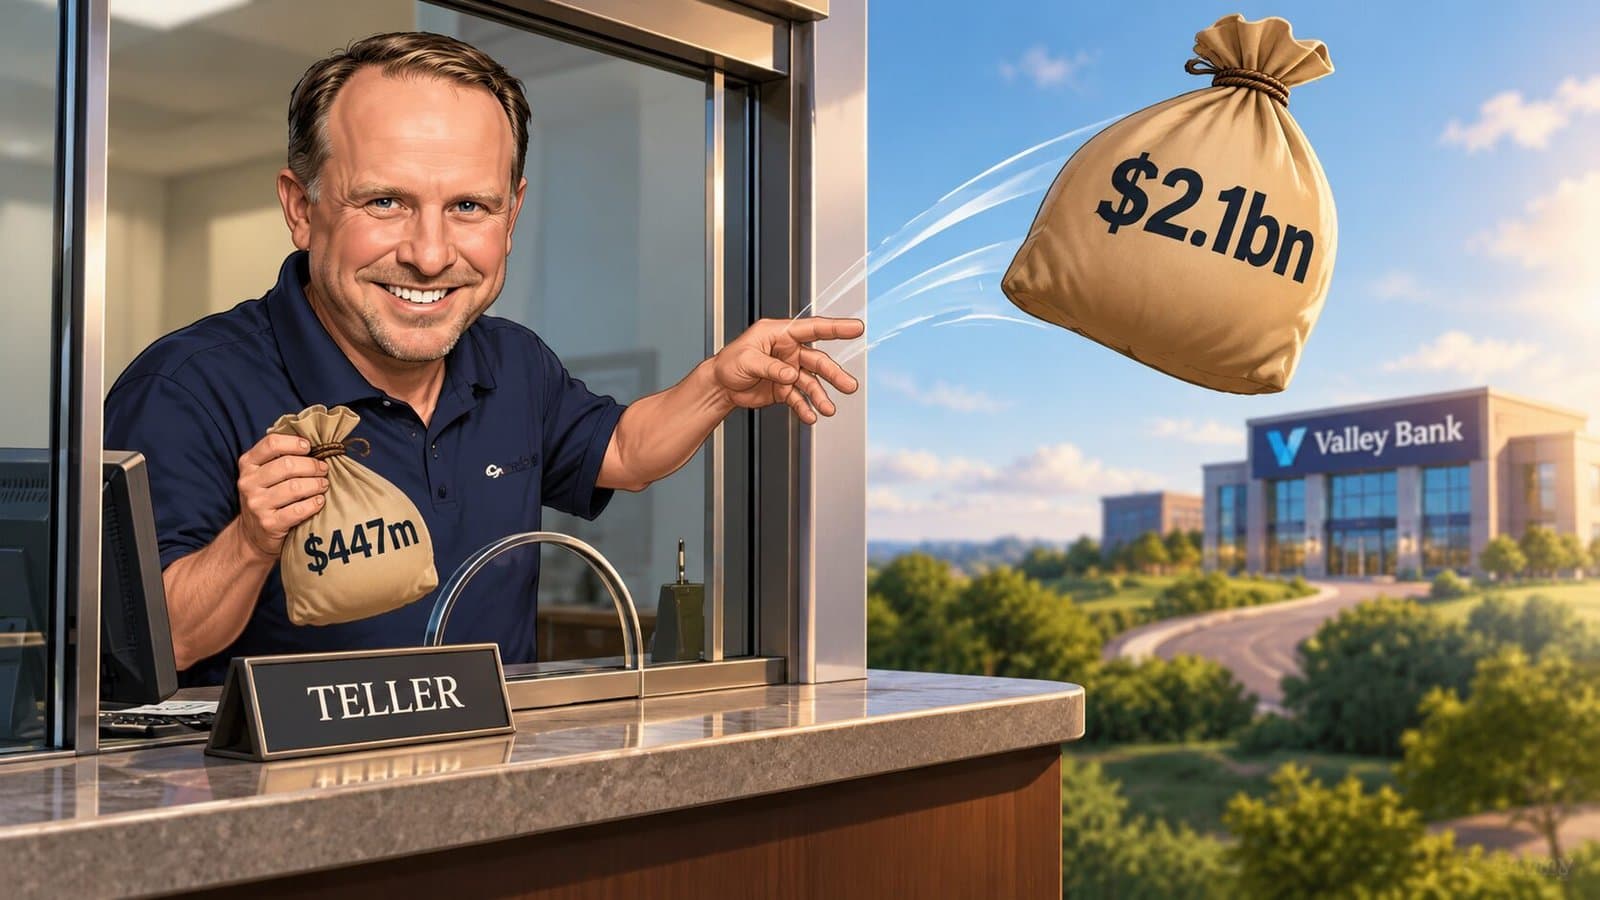
The figure traveling with the deal was Bluevine’s $2.1 billion deposit book. Coastal’s own filing places roughly $447 million of that on its balance sheet. If you own the stock, that gap is the whole question. Either the market priced the headline number, or it priced a risk the filing leaves unaddressed.
Valley pays $340m to swap costly funding for Bluevine’s deposits
Valley agreed to acquire Bluevine for about $340 million, split roughly 75% cash and 25% Valley stock, the companies’ joint press release confirmed. The fintech serves about 175,000 active small-business customers.
Its pull is cheap funding. Bluevine’s deposits cost 1.44% in the second quarter of 2026, 84 basis points below Valley’s 2.28%, Valley’s investor presentation showed. Valley guided to roughly 8% accretion to estimated 2028 earnings per share. It expects about 5% tangible book value dilution at closing and a three-year earnback, the release stated.
Valley’s own shareholders were not cheering either. The stock closed at $12.78 on 28 September, down 2.29% from $13.08, Yahoo Finance data showed.
![Caricature portrait of Ira Robbins, chairman, president and CEO of Valley National Bancorp]](/media/wp-content/uploads/2026/09/ChatGPT-Image-Sep-29-2026-07_42_42-AM-1024x576.png)
“It is expected to enhance our core funding capabilities.” — Ira Robbins, chairman, president and CEO, Valley National Bancorp, in the company’s press release
Robbins is highlighting the deal’s funding benefit. Valley runs a 107% loan-to-core-deposits ratio, and CFO Travis Lan told analysts the bank’s constraint is funding loans rather than finding them, American Banker reported.
More on bank and fintech deals:
Novo Nordisk stock falls as 2026 plan targets peer growth
Coastal’s filing puts $447m on its books, not $2.1bn
Coastal answered with its own Form 8-K the same day. About $447 million of Bluevine-related deposits sat on Coastal Community Bank’s balance sheet as of 25 September 2026, the filing disclosed.
That balance moves with customer activity and with the bank’s deposit sweep arrangements, the filing explained. A sweep places customer cash at other banks, which keeps it off the sponsor bank’s own books.
Valley’s figure is dated 30 June, and Coastal’s 25 September, yet the on-balance-sheet share still works out to roughly a fifth of the headline book. Coastal said it does not currently expect a material adverse effect on its liquidity or funding, citing 22 active CCBX partners and its ability to recall swept deposits.
Key figures behind Bluevine’s exit from Coastal
- Deal value: about $340m, roughly 75% cash and 25% Valley stock (Valley press release)
- Bluevine deposits: $2.1bn as of 30 June 2026 (Valley investor presentation)
- Held on Coastal’s balance sheet: about $447m as of 25 September 2026 (Coastal Form 8-K)
- Cost of deposits, Q2 2026: Bluevine 1.44% against Valley 2.28% (Valley investor presentation)
- Coastal total assets: $5.45bn at the time of the deal (American Banker)
- Valley share price: $12.78 at the 28 September 2026 close, down 2.29% from $13.08 (Yahoo Finance)
- Coastal share price: $37.55 at the 28 September 2026 close, down 16.23% from $44.82 (Yahoo Finance)
Sources: Valley National Bancorp, Coastal Financial Corporation, American Banker, Yahoo Finance
Analysts put the earnings hit well below the price drop
Raymond James estimated that the Bluevine exit would reduce Coastal’s annualized earnings by 22 to 52 cents a share, GuruFocus reported. The firm kept its Outperform rating.
Keefe, Bruyette & Woods called the decline an overreaction and held its Outperform rating with a $53 target, GuruFocus noted. The firm argued Coastal can replace the lost income.
The arithmetic supports that read on its face. The 28 September slide took $7.28 off each share, which prices the Raymond James range at roughly 14 to 33 times a single year of lost earnings. The $447 million also equals about 8% of Coastal’s $5.45 billion in total assets.
Where the price targets sit against the close
Both analyst targets sit well above the 28 September close of $37.55. KBW’s $53 target, reaffirmed after the Bluevine news, is about 41% higher. Raymond James set its $50 target on 31 July, about 33% above the close, Stock Observer reported.
Estimates have also moved lower, with Yahoo Finance currently showing a 2027 average EPS estimate of $5.81, based on four analysts.
Coastal’s filing is silent on Bluevine’s fee income
The 8-K does not quantify the fee revenue specifically generated by Bluevine, which KBW described as a key driver of the segment’s transaction fee growth, GuruFocus indicated.
Valley’s deck hints at its size. It books a roughly $20 million annual pre-tax hit from the Durbin Amendment, which caps debit interchange at banks with more than $10 billion in assets.
The presentation says the roughly $20 million represents a 50% reduction in Durbin-related income. Coastal, at $5.45 billion in assets, sits below the cap, and it has not disclosed how much of that interchange it keeps.
A second-quarter loss had already broken the stock
Coastal posted a second-quarter 2026 loss of $2.76 a share after a $68.8 million credit expense tied to a single CCBX partner, Investing.com reported. The shares fell 44% on that release.
Raymond James analyst David Feaster Jr. warned the market would keep a higher risk premium on CCBX until management proves the loss was isolated, the outlet noted on 31 July.
Law firm Bleichmar Fonti & Auld announced an investigation into potential securities claims tied to CCBX disclosures on 25 September, according to its GlobeNewswire release. An investigation announcement is not a finding of wrongdoing.
“We are excited for Bluevine. This is a success story.” — Eric Sprink, CEO, Coastal Financial, told American Banker
Sprink acknowledged the deal will weigh on Coastal’s finances but put no figure on it, the outlet reported.
Bluevine deal highlights a risk for sponsor banks
KBW tied the decline to overly pessimistic sentiment toward banking-as-a-service sponsors as a group, not to Coastal alone, GuruFocus reported. The exposure is structural. A fintech that outgrows its sponsor bank can take its deposits and fee income to an acquirer or to its own charter.
Robbins framed the deal in exactly those terms, saying Valley chose to combine with Bluevine rather than wait for chartered fintechs to compete, Banking Dive reported.
Valley’s timeline gives Coastal until mid-2027
Valley expects to close in early first-quarter 2027. The transaction does not require conventional bank regulatory or shareholder approval and remains subject to antitrust clearance and other customary conditions. Bluevine’s partner bank program ends at closing.
The related deposits then move to Valley Bank within 180 days, the presentation explained. That puts the full exit around mid-2027.
What the Bluevine exit means for Coastal shareholders
About $447 million of Bluevine-related deposits were on Coastal’s balance sheet as of 25 September, not the full $2.1 billion attached to the deal. Raymond James sizes the earnings cost at 22 to 52 cents a share, well below the $7.28 price drop. The unquantified piece is the fee income Bluevine generates for CCBX.
If you hold the stock, two dates settle the argument. Coastal’s third-quarter report carries the detail it promised, and Valley’s early-2027 close starts a 180-day clock on the deposits.